






ECB holds at 2.50%: what it means for Irish mortgages and savings before 17 December
The European Central Bank kept its deposit rate at 2.50% on 29 October after two rises this year. The next decision is on 17 December. Here is where Irish mortgage and savings rates stand, and what to check now.
50% of our commission goes to the charity or club you pick.Change
Pick a charity and we'll give them 50% of our commission.
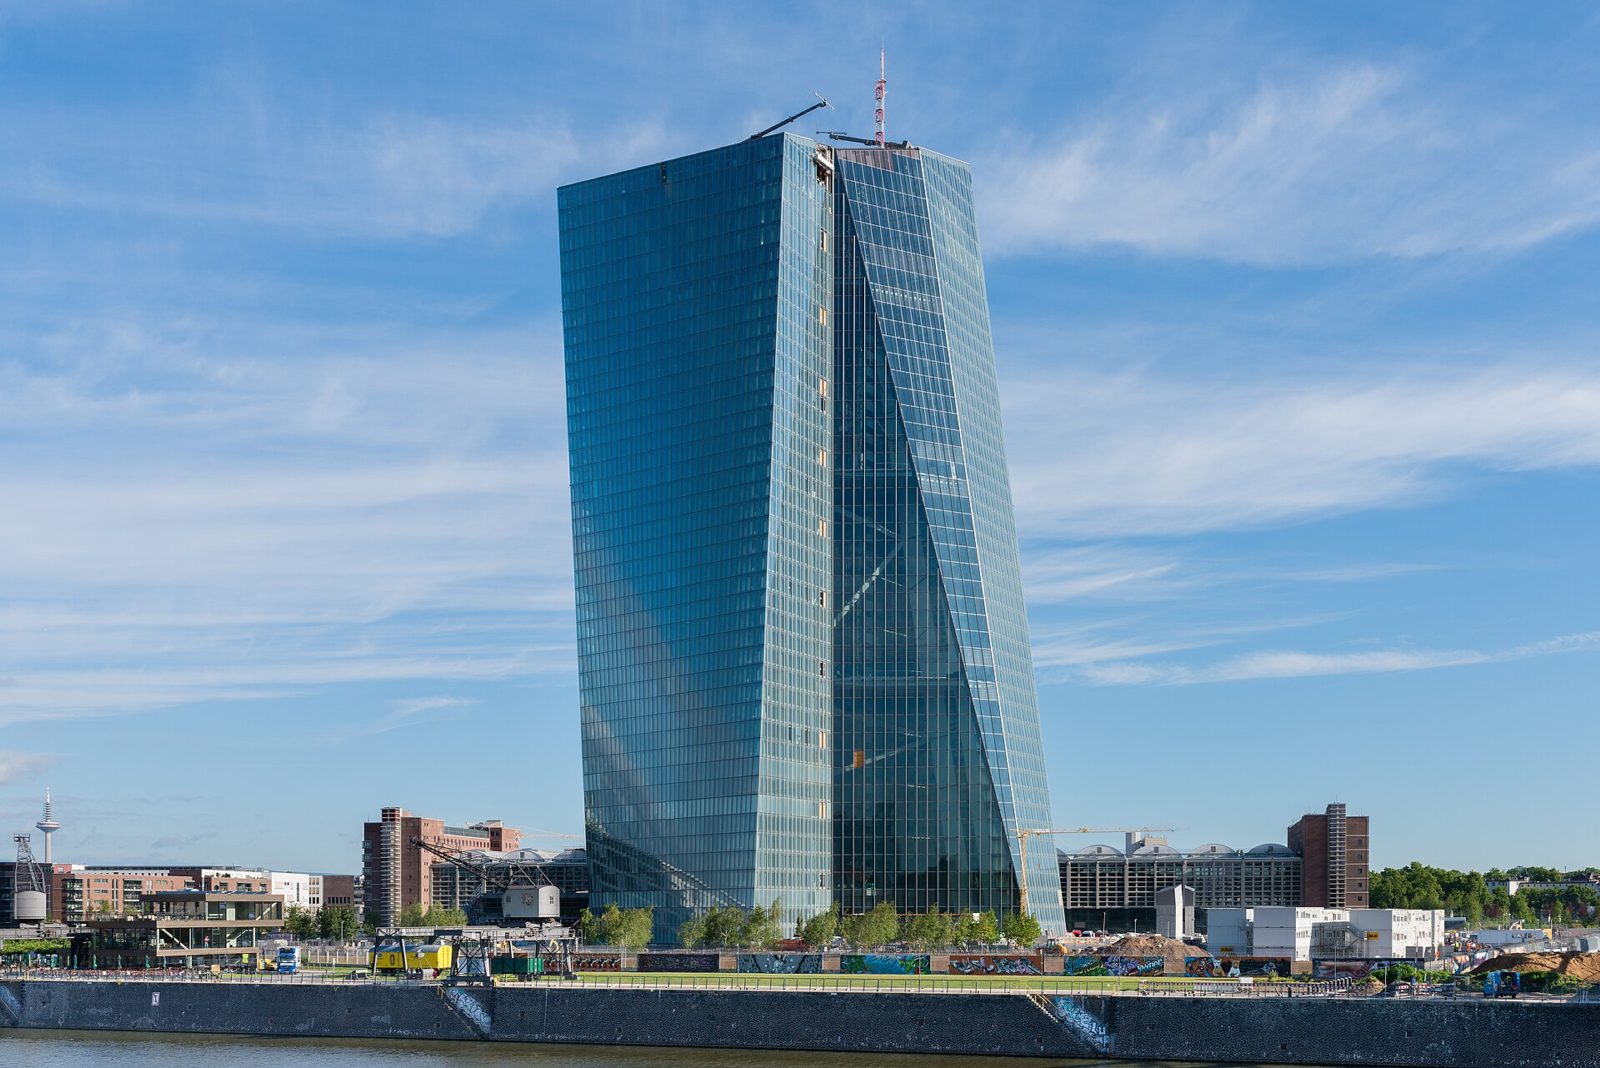
The European Central Bank (ECB) left its three key interest rates unchanged on 29 October 2026. The deposit facility rate stays at 2.50%. The main refinancing rate is 2.65% and the marginal lending rate is 2.90%. The next decision is due on 17 December 2026.
How we got here
The ECB's own table of official rates shows two rises this year. The deposit rate went from 2.00% to 2.25% with effect from 17 June 2026, then to 2.50% from 16 September 2026. It had been at 2.00% since 11 June 2025.
In its 29 October statement the ECB said energy prices have continued to rise, creating "upside risks to the inflation outlook and downside risks to the growth outlook". It also said financing conditions had tightened since its previous meeting. It will decide "meeting-by-meeting" and is "not pre-committing to a particular rate path". In other words, December could bring a hold, a rise or a cut.
Inflation in Ireland is running well above the ECB's 2% target. The Central Statistics Office (CSO) says consumer prices rose 4.3% in the 12 months to October 2026, the highest rate since December 2023.
Where Irish rates are now
The Central Bank of Ireland's latest retail interest rate figures cover September 2026:
- New mortgages: an average of 3.52%, down 0.01 points on August and 0.07 points lower than a year earlier. The euro area average was 3.64%.
- Fixed rates: 94% of new mortgage lending was fixed, at an average of 3.47%.
- Variable rates: new variable mortgages averaged 4.30%, up 0.14 points in a month and 0.22 points in a year.
- Switchers: renegotiated fixed-rate mortgages averaged 3.23%.
- Personal loans: new consumer loans averaged 7.44%.
- Savings: household overnight (instant access) deposits paid an average of 0.23%. Between September 2025 and September 2026, the average rate on new Irish fixed-term deposits rose by 0.10 points, while the euro area average rose by 0.59 points to 2.37%.
A worked example
These are averages, so your own rate will differ, but they show where the gaps are.
A €200,000 mortgage. The gap between the average new variable rate (4.30%) and the average new fixed rate (3.47%) is 0.83 points. On a €200,000 balance, that is about €1,660 of interest in a year before any capital is repaid. If you are on a variable rate and your lender offers a fixed rate near the average, the difference is worth a phone call.
€10,000 in savings. At the 0.23% average for instant access, €10,000 earns €23 in a year. Deposit Interest Retention Tax (DIRT) is 33%, which leaves €15.41. At the 2.37% euro area average for new fixed-term deposits, the same €10,000 would earn €237 before tax, or €158.79 after DIRT. With prices up 4.3% in a year, neither keeps pace with inflation, but one loses a lot less.
What to do now
- Find your mortgage rate and type on your latest statement. If you are on a variable rate, ask your lender what fixed rates it offers you today.
- If your fixed term ends in the next few months, ask for your options in writing before it rolls onto a variable rate.
- Check what your savings actually earn. If it is close to the 0.23% average, compare fixed-term and notice accounts using the CCPC's savings comparison tool.
- Remember that the Deposit Guarantee Scheme covers eligible deposits up to €100,000 per person per institution. If you hold more, the CCPC suggests spreading it across providers.
- Put 17 December in your diary. The ECB announces its decision that day, followed by a press conference.
Questions
Does an ECB decision change my mortgage rate? That depends on your mortgage contract, which sets out whether your rate is fixed for a term, variable or a tracker, and how it can change. The Central Bank's figures show 94% of new Irish mortgage lending in September was at fixed rates.
Why are Irish savings rates so low compared with the euro area? The Central Bank's figures show Irish rates on new fixed-term deposits rose much less than the euro area average in the year to September. It doesn't give a reason, but it does show the value of shopping around.
Is there tax on savings interest? Yes. The CCPC says interest on savings in Ireland is generally subject to DIRT at 33%, usually deducted automatically.
Ways to save
Higher rates make day-to-day costs matter more. Our look at where prices are rising fastest covers fuel and energy. And because scammers often pose as banks, read our guide to the *21* call-forwarding scam before you talk to anyone about switching.
When you shop through Promo Magpie, part of the commission the shop pays us goes to the charity or club you pick. You pay the same price.
Sources: ECB, Monetary policy decisions, 29 October 2026, ECB, Key ECB interest rates, checked 16 November 2026, ECB, Governing Council meeting calendar, 16 November 2026, Central Bank of Ireland, Retail Interest Rates September 2026, 16 November 2026, CSO, Consumer Price Index October 2026, 11 November 2026, CCPC, Compare savings accounts, 16 November 2026
More on your rights when you shop
The Thursday email
Every Thursday: the best codes from the brands you shop at. After you sign up, pick your brands and whether you want codes, hot deals, free delivery or student offers. No spam, unsubscribe in one click.